

Sumio: Net Worth Tracker

- 5.00 Reviews
- 3.8
- Downloads
- 10,000+
Our take on Sumio: Net Worth Tracker from Appgk
I found Sumio: Net Worth Tracker most interesting when I stopped treating it as a general finance app and used it for one clear job: turning scattered personal assets into a single view of my financial position. That focus matters. Instead of checking a bank balance, an investment account, a fund, and other assets separately, I could use one place to think about the bigger picture.
Sumio is a free finance app from Fiduciary, available for Android users on version 7.0 or later. It has a 3.8 average from around 80 ratings and more than 10 thousand installs, so it is still a relatively small product rather than a dominant household name. That does not make it uninteresting, but it does set the right expectation: I see it as a focused tracking tool, not a complete replacement for a bank, broker, tax service, or professional financial adviser.
Seeing net worth as one usable number
The central capability is simple to describe but surprisingly useful in daily life. Sumio lets me calculate and track net worth by bringing investments, stocks, funds, assets, and related financial values into one overview. The benefit is not merely having another balance on screen. It is being able to ask a more meaningful question: after considering what I own, what is my financial position right now?
That distinction helped me avoid a common mistake. A checking account can look healthy while investments are neglected, or a portfolio can appear impressive while debts and major obligations are ignored elsewhere. A net-worth view encourages a wider perspective. I found it particularly helpful for separating short-term spending money from longer-term progress.
Best Parts of Sumio: Net Worth Tracker
Things to Keep in Mind About Sumio: Net Worth Tracker
The strongest idea in Sumio is the change from account watching to financial direction. A single balance tells me what is available today. A net-worth record helps me judge whether my overall position is improving, staying flat, or moving backward. Those are different questions, and the second one is usually more useful when I am reviewing goals such as building savings, investing consistently, or preparing for a large purchase.
The app’s store summary also points toward portfolio and asset tracking, which makes it more suitable for people whose finances are spread across several categories. Someone with only one everyday account may not gain much from this broader view. Someone with cash savings, investments, funds, and valuable assets can get a clearer mental model from putting those pieces together.
News and Features Related to Sumio: Net Worth Tracker

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
What the overview changes in everyday decisions
In practice, I would not open Sumio to decide whether I can afford a small lunch. I would use it for decisions that are easy to misunderstand when viewed through one account alone. For example, before increasing an investment contribution, I could look at the wider balance between liquid money, invested money, and other assets. That does not tell me what I should buy, but it gives better context for the decision.
The same applies to lifestyle changes. If I am considering a move, a vehicle purchase, or a period of reduced income, tracking net worth can reveal whether the plan is supported by real resources or only by a temporarily high cash balance. The app is most valuable when I use its overview to slow down a decision rather than to chase a daily number.
Don't want to read the full review?
There is also a psychological advantage. Financial accounts often encourage short-term reactions: a market drop feels alarming, while a salary deposit feels reassuring. A broader net-worth record can make those events feel less isolated. I still need to understand what caused a change, but I am less likely to mistake one account’s movement for the complete state of my finances.
How I would use it in practice
I would begin by deciding what I want the tracker to answer. If I add every financial detail without a purpose, the result may become a cluttered list rather than a useful overview. A better starting point is to identify the main groups I want to monitor: everyday money, investments, funds, stocks, and significant assets. The exact categories that matter will depend on the person, but the principle is the same: include information that helps explain financial progress.
Screenshots
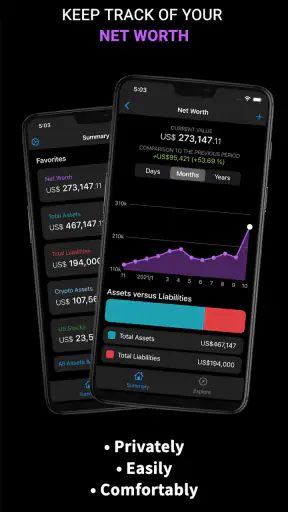
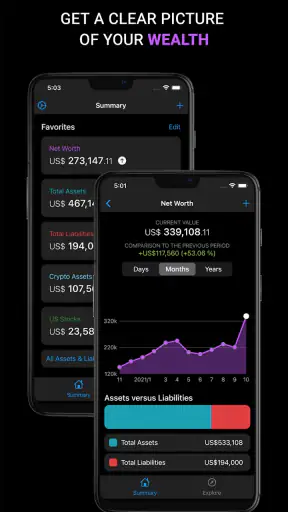
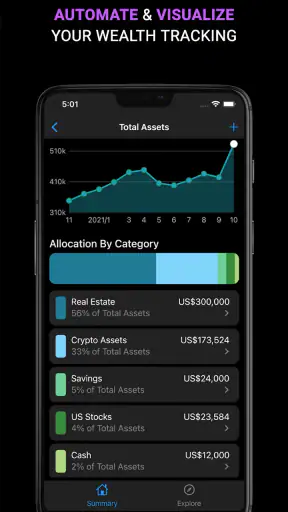
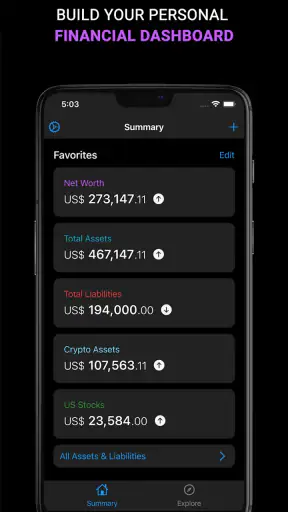
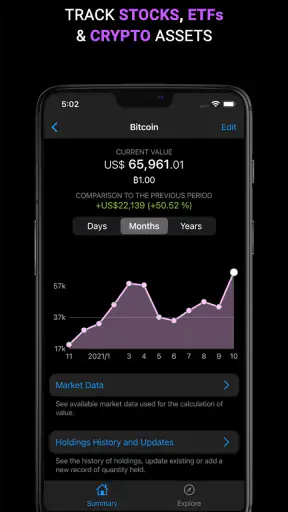
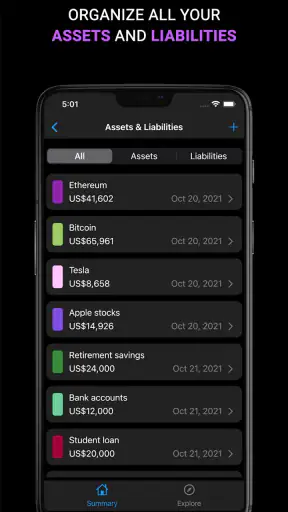
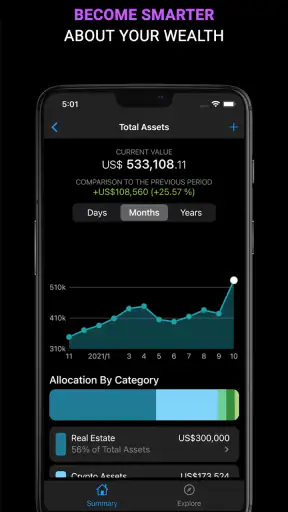
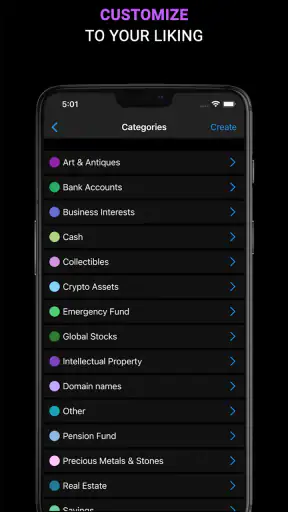
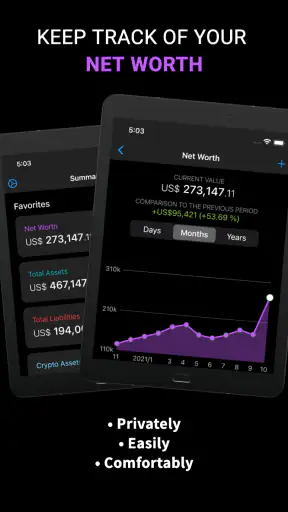
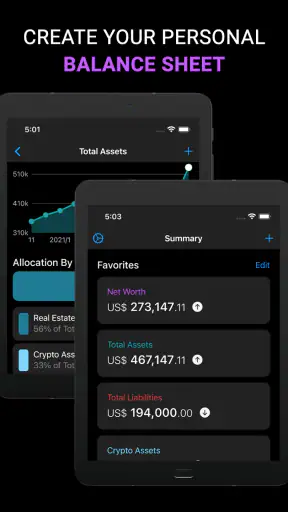
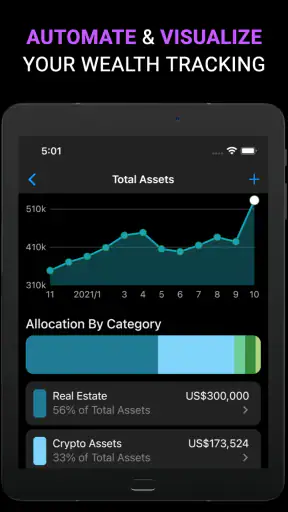
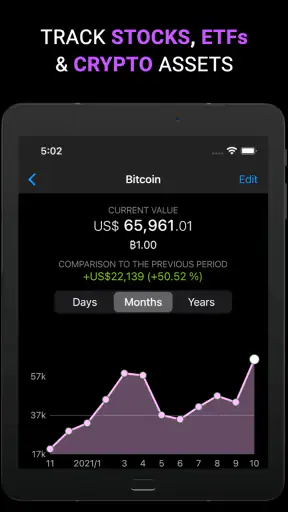
After that, I would establish a baseline and record it consistently. Net worth is only meaningful as a tracking concept when I can compare one point in time with another. The important habit is not opening the app repeatedly during a volatile market day. It is returning on a sensible schedule and using the same approach each time.
One practical tip is to separate valuation from emotion. If an investment changes in value, I would record the current figure rather than adjusting the number because I feel optimistic or worried. Otherwise, the tracker becomes a diary of expectations instead of a picture of what I actually hold. Sumio can organize the information, but the quality of the result still depends on disciplined entries.
Another useful workflow is to review the total together with its components. A rising net worth is encouraging, but it can hide an unhealthy concentration in one asset or an unusually low cash reserve. A falling total may be less concerning if it reflects a planned purchase or a temporary market movement. The overall number starts the conversation; the breakdown explains it.
This is where I think the app’s focused design can be both helpful and limiting. A dedicated tracker keeps attention on the financial picture, but it does not remove the need for judgment. I would not treat the displayed total as an automatic recommendation to invest more, sell something, or change my budget. It is a reference point, not a financial adviser.
A realistic monthly routine
Imagine someone who receives income in one account, keeps emergency savings elsewhere, owns a few funds, and has a valuable asset such as a car. During the month, the everyday account rises and falls so often that it becomes hard to see progress. At a regular monthly review, that person could update the relevant figures in Sumio and compare the new overall position with the previous review.
The useful discovery might not be a dramatic increase. It could be that the investment account is growing while cash reserves are shrinking, or that a large asset makes the total look stronger than the amount readily available for emergencies. That insight can lead to a better question: is the balance between accessible money and long-term holdings appropriate for my current situation?
I would also use notes outside the app’s core total, if needed, to remember why an unusual change occurred. A large purchase, a transfer, or a market movement can otherwise look mysterious later. This is one of the less obvious lessons of tracking: historical context is almost as important as the number itself. A clean record is easier to trust when I understand its exceptions.
For couples or families, I would be careful about what the combined figure means. A shared net-worth view can support planning, but only if both people agree on which assets are included and how they are valued. Mixing personal and shared property without a clear rule can create a misleading total. Sumio can help display the agreed picture, but the agreement has to come first.
The situation where Sumio makes the most sense
The best scenario is a person who has started investing or building assets but feels that financial information is scattered. This user does not necessarily need complex analysis. They need a calm, repeatable way to see the relationship between cash, investments, funds, stocks, and other holdings.
For that person, Sumio can become a monthly checkpoint. The process might take only a short session: review the current values, update the relevant entries, compare the overall direction, and identify one action for the next period. That action could be increasing savings, rebuilding cash reserves, checking an investment allocation, or simply staying consistent. The value comes from turning vague concern into an observable routine.
I also see a strong use case for people who are financially organized in separate places but lack a summary. They may already use a banking app for transactions and a broker’s app for investments. Those tools are often excellent at showing activity inside their own systems, but they do not always answer how everything fits together. Sumio’s role is to provide that wider frame.
It can also help before a major personal milestone. Someone preparing for a home deposit, a career break, or a move may want to measure progress without constantly switching between services. The tracker will not replace a detailed affordability calculation, yet it can show whether the person’s overall position is moving toward the goal.
A less obvious benefit is that it may expose dependence on assets that are difficult to access quickly. A person can feel wealthy because the total includes investments or valuable property, while having little available cash. By looking at the components rather than celebrating the headline number, Sumio can encourage more realistic planning around emergencies and near-term bills.
When I would choose another tool
I would not choose Sumio as my only financial tool if I needed automatic banking operations, detailed transaction categorization, bill management, tax preparation, or direct trading. A bank app is better for moving money and checking cleared transactions. A brokerage platform is better for orders, holdings, and market execution. A budgeting app may be better for assigning every purchase to a spending category.
I would also hesitate if I wanted advanced investment research or portfolio analytics. A net-worth tracker can show the result of my financial choices, but it is not the same as researching risk, comparing funds, or evaluating a company. For those tasks, specialized services are more appropriate. Sumio works best beside those tools, not in place of all of them.
People who dislike manual financial maintenance should think carefully before starting. The usefulness of any tracker declines when values are entered inconsistently or forgotten for long periods. If the main need is automatic synchronization, the best alternative may be a service built specifically around connected accounts, provided the user is comfortable with that model. Sumio’s appeal is stronger for someone who wants deliberate control over the figures being tracked.
Trade-offs I noticed before recommending it
The first trade-off is simplicity versus depth. A focused net-worth app can feel less overwhelming than a full personal-finance suite, but it may not satisfy someone who wants every financial task in one place. I like the narrower purpose because it keeps the review centered on progress, yet I would not mistake that focus for comprehensive money management.
The second trade-off is clarity versus precision. A single total is easy to understand, but it can create false confidence if the underlying values are outdated or estimated too loosely. Assets do not all have the same liquidity, stability, or valuation method. Cash is straightforward; a stock or fund can move; a personal asset may be harder to price. I would therefore treat the total as a practical estimate and pay attention to the categories behind it.
The third trade-off concerns frequency. Updating too often can encourage anxiety and overreaction, especially when investments fluctuate. Updating too rarely makes the record stale. I would favor a regular review rhythm that matches the purpose of the tracker, such as a monthly or quarterly check, rather than opening it whenever the market moves.
There is also a cost consideration. The app itself is free, while in-app purchases range from around three dollars to around thirty dollars per item. That means I would inspect the purchase screen carefully before paying for anything and decide whether the added value fits my actual routine. A free starting point is useful, but the presence of optional purchases means the complete experience may depend on which functions a user wants.
The age rating is Everyone, which makes the app broadly accessible from a content perspective. That should not be confused with financial suitability for every user. A young person, a beginner, and an experienced investor may all open the same tracker, but they will need different habits and expectations. The app can organize figures; it cannot teach every financial concept or make decisions responsibly on the user’s behalf.
Sumio was released on December 7, 2021, and the current version is 1.9.18. I mention that because version context matters when judging a smaller finance product: the experience can change as the developer refines it. I would keep the app updated and review any changes that affect how I record or interpret my figures, especially if I rely on it for long-term history.
Who gets the most value from this tracker
I think Sumio is a good match for an individual who wants a consolidated view without turning financial review into a full-time project. It is especially relevant to new investors, people with several asset types, and anyone who keeps checking separate accounts but still cannot answer whether their overall position is improving.
It may also suit users who prefer intentional record-keeping. Manually reviewing assets can feel like extra work, but it gives me a chance to think about what each number represents. That process can be more valuable than passive data collection because it makes me notice concentration, liquidity, and changes in priorities.
Beginners should approach the app with one modest goal: establish a reliable baseline and learn to interpret movement over time. I would not begin by trying to optimize everything. First, I would make the record consistent. Then I would use the overview to identify one financial question at a time. This prevents the app from becoming another source of confusing numbers.
More experienced users may appreciate it as a high-level dashboard alongside specialized services. They can keep using their bank and investment platforms for detailed work while using Sumio to answer the broader question of how those pieces affect total wealth. That division of labor is sensible and avoids forcing one app to perform every financial task.
On the other hand, I would skip it if I only need a spending ledger, if I require fully automated account feeds, or if I want professional-grade portfolio analysis. I would also skip it if I know I will not maintain the figures. In those situations, a tool designed around the specific missing function would probably be more useful than a net-worth tracker.
My final view is positive but deliberately measured. Sumio does not impress me because it promises to solve personal finance in one tap. It earns its place by making a scattered financial picture easier to review. If you want a simple checkpoint for your overall position rather than a complete banking or investing replacement, it is worth trying for free. Just keep the numbers current, interpret the total alongside its parts, and use the app to support decisions rather than letting one figure make them for you.
Sumio: Net Worth Tracker FAQ
What is Sumio: Net Worth Tracker used for?
Sumio: Net Worth Tracker is a personal finance app designed to help you monitor your overall financial position in one place. You can record assets such as bank balances, investments, property, and digital currencies, then subtract debts and liabilities to estimate your net worth. It is mainly useful for tracking progress over time rather than replacing a professional financial adviser.
How do I add my accounts and assets to Sumio?
After opening Sumio, you can create financial entries for cash, bank accounts, investments, real estate, vehicles, cryptocurrencies, loans, credit cards, and other valuables or debts. Depending on the available integration options, some information may need to be entered manually. Users should review categories and update balances regularly because the accuracy of the dashboard depends on the information they provide.
Does Sumio connect directly to banks or investment accounts?
Sumio may offer account connection or synchronization features depending on your country, device, subscription plan, and the financial institutions supported by the app. Availability can change, so you should check the current connection list before downloading. If automatic linking is unavailable, you can still use the app by entering balances and transactions manually, although this requires more frequent maintenance.
Is Sumio: Net Worth Tracker free to use?
Sumio can generally be downloaded and used with basic functionality, but some advanced tools may require a paid subscription or in-app purchase. Premium features can include expanded tracking options, additional reports, synchronization capabilities, or more detailed financial insights. Before subscribing, review the pricing, renewal terms, trial conditions, and cancellation process shown in the App Store or Google Play.
Is my financial information safe in Sumio?
Because Sumio handles sensitive financial information, users should carefully review its privacy policy, security explanations, and permissions before adding personal data. Avoid entering information you are uncomfortable storing in a third-party service, and protect the account with a strong, unique password or available biometric security. The app should be treated as a tracking tool, not as a bank or investment platform.











